Expert commercial property loan and commercial acquisition finance solutions helping Melbourne builders and renovators structure projects without delays.
A commercial property loan broker Melbourne structures finance for office buildings, retail shops, warehouses, industrial units, medical suites and mixed-use properties across Melbourne. Unlike residential lending, commercial finance involves higher deposits (20-35%), shorter loan terms (15-20 years), different valuation methodology based on rental yield and capitalisation rate, and income assessment weighted toward the property’s commercial return. At the current 4.35% RBA cash rate, commercial lending rates on a $1,000,000 property during a standard 30-to-45-day settlement build is far lower than the equivalent standard home loan. Clarity Financial Solutions manages the complete process. Free service. ACL 475676
Difference one: deposits — commercial loans typically require 20% to 35% deposit versus 5% to 20% for residential. Difference two: loan terms — commercial loans are often 15 to 20 years versus 25 to 30 for residential. Difference three: interest rates — commercial rates are 0.50% to 1.50% higher than residential. Difference four: valuation — commercial properties are valued primarily on rental yield and capitalisation rate, not comparable sales. Difference five: income assessment — lenders assess the property’s rental income and the borrower’s ability to service, weighting the commercial yield heavily. A commercial property loan broker Melbournevents cash flow surprises and ensures your builder is paid on schedule:
| Stage | Milestone | What Triggers This Payment |
|---|---|---|
| 1 | Base / Slab | Foundations poured and independently inspected before first drawdown released |
| 2 | Frame | Timber or steel frame erected and council-approved before second drawdown |
| 3 | Lock-Up | External walls, roof, windows and doors installed before third drawdown |
| 4 | Fixing | Internal fittings, plaster, cabinetry and fixtures complete before fourth drawdown |
| 5 | Practical Completion | Builder’s final inspection and handover before fifth drawdown released |
| 6 | Retention | Small percentage held back until all defects are resolved after handover |
Clarity Financial Solutions arranges finance for every commercial property type across Melbourne. Office spaces in the CBD and inner suburbs. Retail shops and shopping strips. Industrial warehouses and factories in the western and south-eastern corridors. Medical and allied health suites. Mixed-use properties combining retail ground floor with residential above. Childcare centres and petrol stations (specialist assets requiring niche lenders). Each office warehouse retail finance Melbourne transaction has unique lending requirements — and the right lender varies by property type. A commercial mortgage Melbournee loans. As a specialist commercial lending adviser Melbourne homeowners and builders trust, we manage the entire finance structure – from initial lender approval through to the final progress payment at handover.
Unlike a standard mortgage where funds are released in full at settlement, a commercial property loan releases funds progressively across defined commercial property loan stages. Without correct structuring from the outset, progress payment delays stop work on site, builder relationships deteriorate and project timelines collapse entirely.
As an ASIC-registered credit representative under ACL 475676, our advice is independent, commercial acquisition-specific and compliance-driven.
A mixed use property loan Melbourne covers assets such as a retail shop with apartments above — fall between residential and commercial lending. Some lenders classify them as commercial (higher deposit, shorter term). Others apply a blended assessment treating each component separately. The classification depends on the proportion of commercial versus residential floor area and income. A commercial property loan broker Melbourne specialist identifies which lenders classify your mixed use property loan Melbourne most favourably. Office warehouse retail finance Melbourne lending for mixed-usent approach to standard commercial property loans. The existing property must be discharged or refinanced before demolition begins, land value must support the new build LVR assessment, and lender policy on commercial acquisition sequencing varies significantly across the market.
As your commercial lending broker Melbourne team, we identify lenders whose lending policy supports your specific commercial acquisition timeline – preventing approval delays that stop demolition and build commencement before the project even begins.
Our process focuses on build-stage financial alignment – not just loan approval.
For expert advice, connect with Clarity Finance and explore more on Google for structured commercial finance guidance.
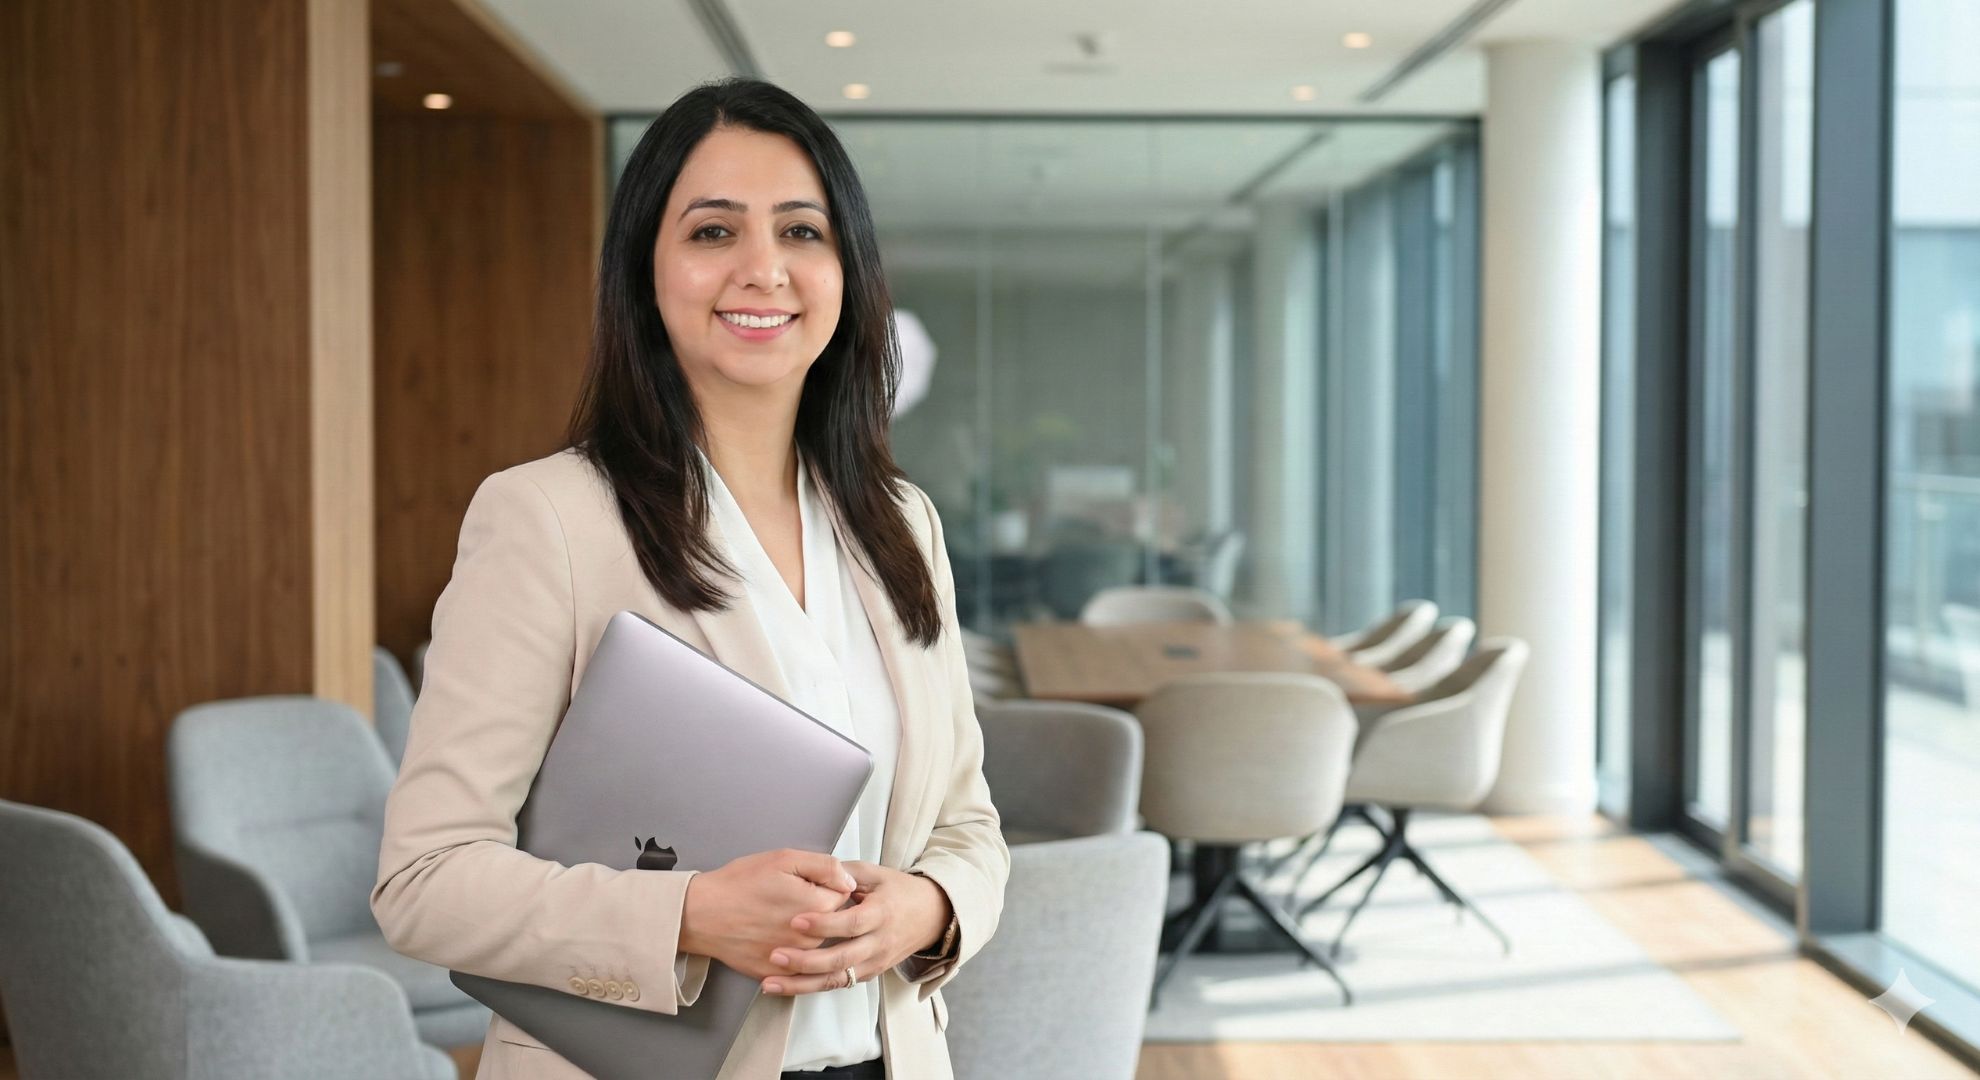
CPA Australia Member | Licensed Mortgage Broker | ACL 475676
MFAA Member | 8+ Years in Finance | 31 Peakview Dr Viewbank VIC 3084
“I started Clarity Financial Solutions because I saw too many Melbourne homeowners
making expensive loan decisions without understanding the tax implications. As a CPA
and mortgage broker, I bridge that gap – structuring your loan the way an accountant
would, not just the way a bank would.”
– Preeti Sidhu, Founder, Clarity Financial Solutions
EXCELLENT Based on 23 reviews
 Posted on Google

 Nikita BrockmullerPreeti at Clarity has been amazing: attentive, honest, breaks everything down in way that helps us understand and feel genuinely empowered in the decisions we're making.Posted on Google
 PreetahI've had the pleasure of getting to know Preeti Sidhu from Clarity Financial Solutions through Biz Growth Network and have been consistently impressed by her professionalism, knowledge, and genuine commitment to helping her clients. Preeti has developed a strong niche in assisting self-employed borrowers, understanding the unique challenges business owners face when applying for a home loan or investment loan. Her extensive lending knowledge, attention to detail, and ability to simplify complex finance concepts make her a trusted mortgage broker. If you're self-employed and looking for expert mortgage advice, guidance on borrowing capacity, or assistance securing the right home loan solution, I would highly recommend speaking with Preeti at Clarity Financial Solutions. She genuinely cares about her clients and works hard to help them achieve their property and financial goals.Posted on Google
 ShwethaPreeti Sidhu is a broker who genuinely cares about the local business community around Bundoora and beyond. She is professional, approachable, responsive and always goes the extra mile to understand what her clients need. As a broker she is proactive, knowledgeable and always willing to help, making the whole process easy and stress-free. I would highly recommend Preeti to anyone looking for a trusted, professional and approachable broker. 10/10!Posted on Google
 Dalveer SinghPreeti was really helpful throughout the home loan process. She explained everything clearly, was easy to deal with, and kept me updated along the way. Very happy with her service and would definitely recommend her.Posted on Google
 Pawan SidhuI had an excellent experience working with Preeti.She is incredibly knowledgeable, with extensive industry experience, and it really shows in the way she guides you through the entire process. She genuinely takes the time to understand her clients' needs and always puts them first. She made what could have been a stressful experience feel smooth and straightforward by taking care of every detail and keeping me informed throughout. Her professionalism, dedication, and attention to detail gave me complete confidence from start to finish. I highly recommend her to anyone looking for a mortgage broker who is experienced, reliable, and truly committed to delivering outstanding service. Thank you Preeti🤗Verified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
Commercial property lending requires specialist broker knowledge because each lender has different policies on acceptable property types, minimum and maximum loan sizes, LVR limits by property category, and income assessment methodology. A warehouse valued at $1.2 million may be approved at 70% LVR by one lender and 65% by another — a $60,000 difference in required deposit. A commercial property loan broker Melbourne with access to 40+ lenders finds the most favourable terms for your specific asset type. Commercial mortgage Melbourneoan. As a specialist commercial finance partner Melbourne homeowners, builders, and developers trust, we structure your finance around every stage of the commercial acquisition process- from land purchase and pre-approval to progress payments and final completion. Our goal is to ensure each payment is released on time, helping your builder maintain momentum without unnecessary funding delays. As an ASIC-registered Credit Representative operating under ACL 475676, we provide independent, compliance-driven lending advice tailored to your commercial acquisition project, financial position, and long-term property goals. This strategic approach helps minimise borrowing risks while keeping your build on schedule and within budget.
Commercial property lending follows different rules to residential — but many investors hold both. Read our complete guide to investing in property in Melbourne 2026 for residential investment strategy. For advice on structuring your portfolio across residential and commercial assets, read our complete guide to home loan structuring.
Commercial property deposits typically range from 20% to 35% of the purchase price — higher than residential. The exact deposit depends on the property type, location, tenant profile and the borrower’s financial strength. A strong tenant on a long lease reduces the lender’s risk and may allow a lower deposit. Vacant commercial properties generally require 30% to 35%. A commercial property loan broker Melbourne assesses your specific situationture. The two loan types operate differently across approval, drawdown, interest calculation and repayment – and choosing the wrong structure creates serious financial complications once the commercial acquisition begins.
Commercial property valuations differ fundamentally from residential. Instead of comparable sales, commercial properties are valued primarily using the capitalisation rate method — the annual net rental income divided by the capitalisation rate for that property type and location. A property earning $80,000 net rent with a 6% cap rate is valued at approximately $1,333,000. The commercial mortgage Melbourne assessment depends heavily on this valuationstanding the commercial property loan stages prevents cash flow surprises and ensures your builder is paid on time at every milestone.
We coordinate lender inspection requests and drawdown submissions at each stage – ensuring your builder is never waiting on payment from an administrative delay.
Commercial loan terms are typically 15 to 20 years — shorter than the standard 25 to 30 year residential term. Interest rates are 0.50% to 1.50% higher than equivalent residential rates. Most commercial loans are structured as interest-only for the first 3 to 5 years to maximise cash flow, with principal-and-interest repayments commencing after the IO period. Some lenders offer 25-year terms for specific commercial property types. Office warehouse retail finance Melbourne lending terms vary by lenderfferent times and require different finance structures depending on whether the land and build contract are with the same vendor or separate parties.
We assess commercial property package loan options across lenders whose lending approval policies support your specific package arrangement – particularly where land settlement occurs well ahead of commercial acquisition commencement.
Yes — many investors grow a commercial portfolio Melbourne using equity from residential property or existing commercial assets. The key is structuring each commercial asset on standalone security to avoid cross-collateralisation. Clarity Financial Solutions ensures each commercial property is independently financed so you can sell, refinance or restructure any single asset without affecting the rest of your portfoliolenders require a licensed builder under a fixed price building contract – because owner-occupier commercial projects carry higher completion, cost and quality risk than professionally managed builds.
Specialist lenders who consider owner-occupier commercial loan australia applications assess owner building permits, project management experience, completion guarantees and personal financial capacity more rigorously than standard commercial property loan applications.
We identify the most suitable specialist lender for your owner-occupier commercial situation – where standard lender policy would otherwise result in an automatic decline.
Clarity Financial Solutions provides independent commercial finance comparison across 40+ lenders — assessing the property type, tenant profile, rental yield, your deposit position and the most suitable loan structure for your commercial portfolio Melbourne investment goals not just interest rates but progress payment policy, LVR thresholds, drawdown processing times and commercial property loan stage requirements unique to each lender.
We structure:
Every commercial finance decision is structured for build completion – not just initial approval.
Self-managed super funds can purchase commercial property under strict rules — the property must be held for investment purposes, the SMSF must have sufficient funds for the deposit, and a limited recourse borrowing arrangement is typically required. Commercial property held in an SMSF offers significant tax advantages including concessional tax rates on rental income and potential CGT exemption in pension phase. A commercial property loan broker Melbourne with SMSF experience structures these transactions correctlyHome Owner Grant Victoria (for new builds under $750,000), a full stamp duty exemption on eligible properties, and the First Home Guarantee (5% deposit, no LMI, Melbourne cap $950,000). The $10,000 FHOG is paid directly to the lender at the first progress payment stage – reducing your effective loan balance from day one. Clarity Financial Solutions structures first home buyer commercial finance to maximise every available concession and grant at the correct build stage, at no cost to you.
Commercial lending works differently. Use these tools to understand your overall borrowing position.
Melbourne’s commercial property market in 2026 presents opportunities across several sectors. Industrial and logistics assets in the western and south-eastern corridors remain in strong demand due to e-commerce growth. CBD office vacancy has stabilised but secondary-grade stock faces repricing. Neighbourhood retail strips with strong foot traffic and long-lease tenants offer stable yields. Medical and childcare assets command premium valuations due to essential-service demand. A commercial property loan broker Melbournetly mistake Melbourne builders make – underestimating the total build cost and running out of funds mid-commercial settlement.
| Build Type | Cost Per M² | 200m² Home | 300m² Home |
|---|---|---|---|
| Project home (standard spec) | $1,800–$2,200 | $360K–$440K | $540K–$660K |
| Custom build (mid-range spec) | $2,500–$3,200 | $500K–$640K | $750K–$960K |
| Luxury custom build | $3,500–$5,000+ | $700K–$1M+ | $1.05M–$1.5M+ |
| Commercial property acquisition (Melbourne metro) | $2,200–$3,500 | $440K–$700K | $660K–$1.05M+ |
Costs are indicative ranges sourced from Melbourne builder quotes, HIA data and Master Builders Victoria, Q1 2026. Actual costs depend on site conditions, council requirements, spec level and builder margin.
As your dedicated commercial property loan broker Melbourne team, we begin with a full property and financial structure review – confirming the most appropriate lender, commercial property loan stage schedule and progress payment process before a single document is submitted.
We negotiate with the biggest names in banking to secure competitive rates and tailored terms for your specific needs.
Buying, refinancing, or investing in property is a major decision – and hearing from others who’ve been through the process can make all the difference. Our clients come to us feeling unsure or overwhelmed, and leave feeling confident, informed, and supported. Their experiences reflect our commitment to clear advice, genuine care, and long-term relationships built on trust.
Follow Clarity Financial Solutions, your trusted Commercial Loan Broker Melbourne partner, for reliable commercial finance insights, expert guidance, and updates to help you structure your build funding with confidence. Learn the differences between Mortgage Broker vs Bank Melbourne to make informed decisions for your home financing needs.
Happy Customer
“Great service! Preeti secured a great deal for our home loan. With her experience working with banks, the process was quick and smooth. She kept us updated regularly, which made everything easier. I would definitely recommend Clarity Financial Solutions for any home loan needs.”
“I had a great experience with Clarity Financial Solutions. I refinanced my loan and received a very competitive discounted interest rate. They provided a variety of bank options to choose from, which made the process easy. The best part was the regular updates — I never had to chase for information. Their service made refinancing simple and stress‑free.”
Unlike regular home loans, commercial property loans are structured based on commercial yield and tenant strength. Speak with a commercial property finance specialist Melbourne specialist to structure your build finance correctly.
No. During the commercial acquisition, you pay interest only on funds drawn down to date, not the full approved loan amount, significantly reducing repayment obligations while your property is being built.
Lenders require standard income documents plus a fixed price building contract, council-approved plans and builder's insurance policy. We help you prepare and collate all required commercial property loan documentation.
Yes. In Victoria the First Home Owner Grant applies to new builds and is paid directly to the lender at the first commercial property loan progress payment stage reducing your borrowing amount.
Design changes called variations after loan approval must usually be funded from savings. Your commercial lending broker Melbourne will advise on variation risk before your building contract is signed.
Owner-occupier commercial options exist through specialist lenders, though approval is more complex. Most lenders require a licensed builder under a fixed price documentation for standard commercial acquisition approval.
Yes. Clarity Financial Solutions coordinates with your builder and lender to manage progress payment stages, ensuring smoother fund releases during the commercial acquisition and reducing delays that can impact your Melbourne building timeline.
A Commercial Loan Broker Melbourne reviews your building contract, council permits, and as an owner-occupier commercial finance broker Melbourne specialist reviews valuation requirements and lender policies before submission. Clarity Financial Solutions helps structure the application correctly to minimise approval issues and commercial acquisition funding delays.
WhatsApp us