Understanding how do construction loans work in Melbourne is essential before signing a building contract. Unlike standard home loans that settle in a single payment, construction loans release funds progressively across build stages – each payment requiring lender inspection and approval. This guide explains the construction loan progress payments explained in detail, the knock down rebuild finance process Melbourne homeowners follow, and how Clarity Financial Solutions manages the entire construction lending process across 40+ lenders.
Construction loan progress payments explained simply: your lender releases funds to your builder at each completed and inspected stage of the build — not upfront as a lump sum. The standard stages are: slab or base (15-20% of contract), frame (20-25%), lock-up (20-25%), fit-out or fixing (20-25%), and completion (5-10%). Each stage must be inspected and signed off by the lender’s valuer before the next payment is released.
How do construction loans work in Melbourne — funds are released progressively across 5 to 6 build stages, with interest charged only on funds drawn. Clarity Financial Solutions manages the entire construction lending process.
During the build, you pay interest only on funds drawn to date — not the full approved loan amount. On a $500,000 construction loan at 6.50%, if $150,000 has been drawn after slab stage, your monthly interest is approximately $813 (on $150,000) rather than $2,708 (on $500,000). This significantly reduces your holding cost during the 8-to-14-month build period. Construction loan progress payments explained this way show why the structure protects both you and the lender.
How do construction loans work in Melbourne differently? Four key differences. First, settlement timing: a standard loan settles in full on one day. A construction loan settles progressively across 5 to 6 stages over 8 to 14 months. Second, interest calculation: you pay interest only on funds drawn, not the full amount. Third, valuation: the lender values the finished property (as-if-complete) before approving the loan, then inspects at each stage to confirm progress matches the approved plans.
Fourth, builder requirements: most lenders require a registered builder with a fixed-price building contract, current builder’s insurance (domestic building insurance in Victoria), and council-approved plans. Some lenders accept cost-plus contracts but with more restrictive LVR limits. Land and construction packages add another layer — the land purchase and construction contract may settle at different times, requiring coordinated lending.
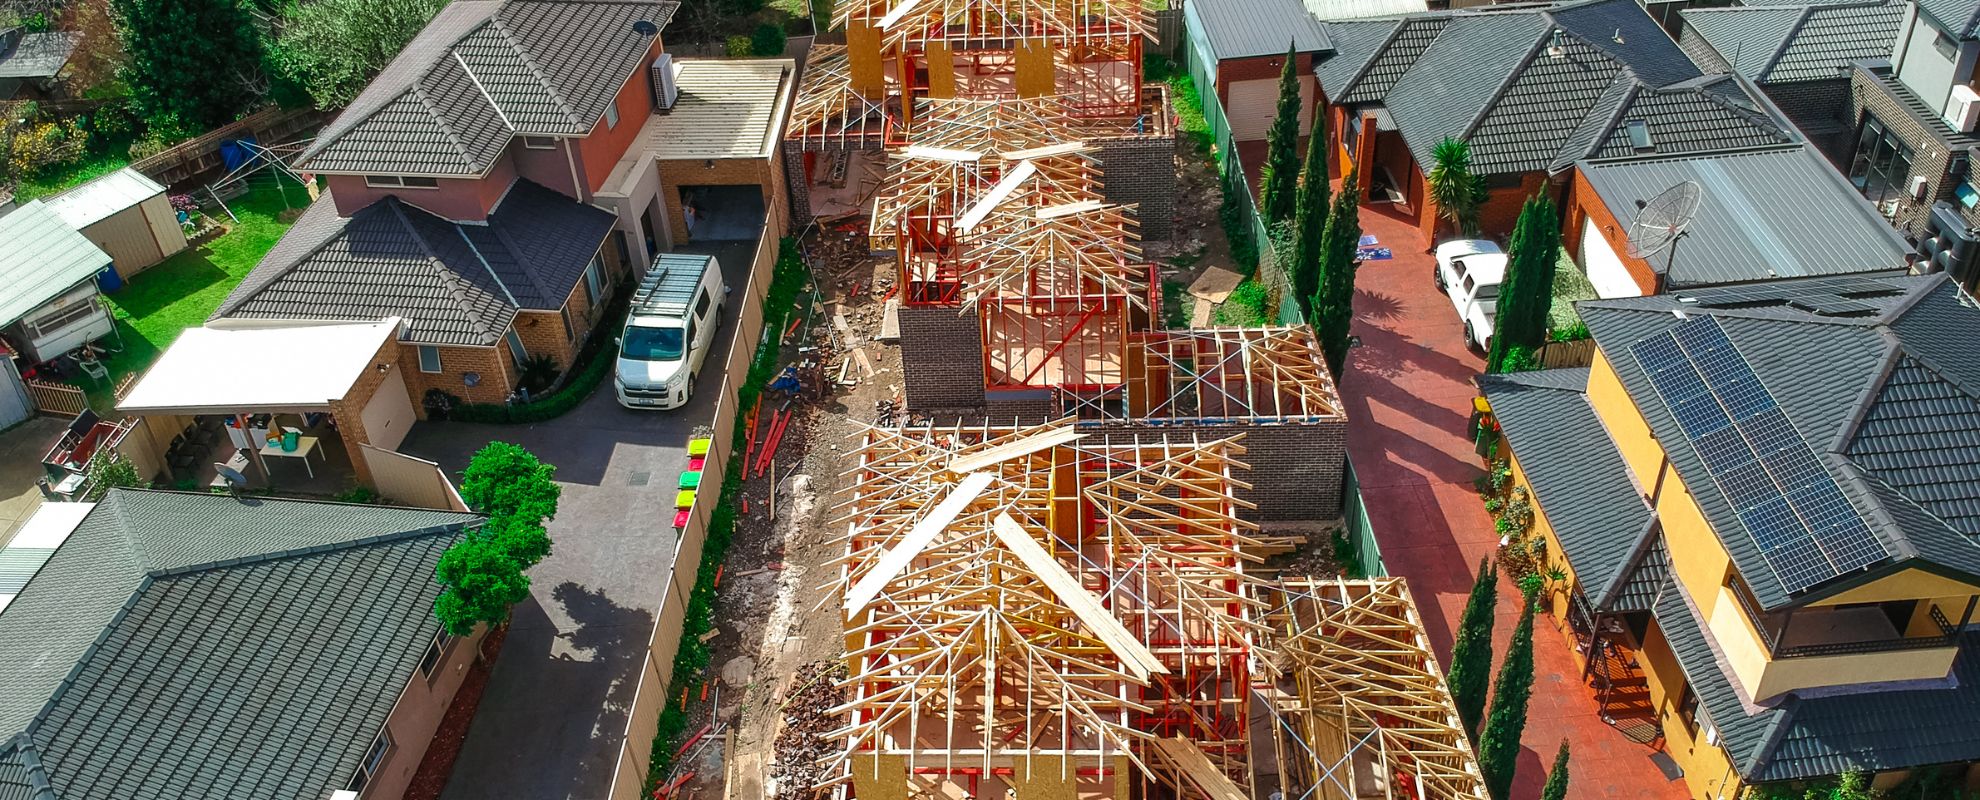
The knock down rebuild finance process Melbourne follows a specific sequence: purchase the existing property (or already own it), obtain council approval for demolition and new build, engage a registered builder with a fixed-price contract, apply for the construction loan based on the as-if-complete value of the new dwelling, demolish the existing structure, and commence the new build with staged progress payments.
The critical difference with knock down rebuild finance process Melbourne is that you already own the land — so there is no separate land purchase. Your existing property is demolished and the construction loan funds the new build on the same site. The lender values the finished dwelling and lends against that future value. During demolition and construction, you need alternative accommodation — the cost of which should be factored into your budget alongside the build costs.
A house and land package combines a land purchase and a building contract from the same developer. The lending is split into two components: the land loan (settled immediately at land purchase) and the construction loan (drawn progressively as the build proceeds). Some lenders combine both into a single facility; others require separate loans.
The advantage of house-and-land is price certainty — the total cost is fixed at contract signing. The lending consideration is that you begin paying interest on the land loan immediately, while the construction loan interest accumulates as stages are drawn. How does the lending work for house-and-land packages requires careful cash flow planning because you are servicing the land loan for months before the build completes and rental income (if investment) or occupancy (if owner-occupier) begins.
Construction loan interest rates in September 2026 are generally the same as standard variable home loan rates — 6.20% to 6.80% depending on the lender and LVR. However, some lenders add a construction loading of 0.10% to 0.20% during the build phase which reverts to the standard rate on completion. Progress payment inspection fees range from $150 to $350 per stage — totalling $750 to $2,100 across a 5-stage build.
Construction loan progress payments explained in cost terms: on a $600,000 build over 12 months with progressive drawdowns, total interest during the build is approximately $18,000 to $24,000 — compared with $39,000 if interest were charged on the full amount from day one. This progressive interest structure saves approximately $15,000 to $21,000 during the build. Clarity Financial Solutions compares construction lending policies across 40+ lenders to find the lowest total build cost.
Mistake one: not getting pre-approval before signing the building contract — if the lender declines, you may forfeit your deposit. Mistake two: choosing a cost-plus contract instead of fixed-price — most lenders restrict LVR on cost-plus builds and the final cost is uncertain. Mistake three: insufficient contingency — allow 10% to 15% above the contract price for variations, landscaping and items excluded from the base quote.
Mistake four: not confirming the builder’s registration, insurance and financial standing before signing — builder insolvency mid-build is devastating. Mistake five: choosing a lender purely on rate without checking their construction lending processing speed — some lenders take 3 to 5 business days per progress claim while others take 10 to 15 days, causing builder payment delays. Clarity Financial Solutions selects lenders with proven construction processing speed.
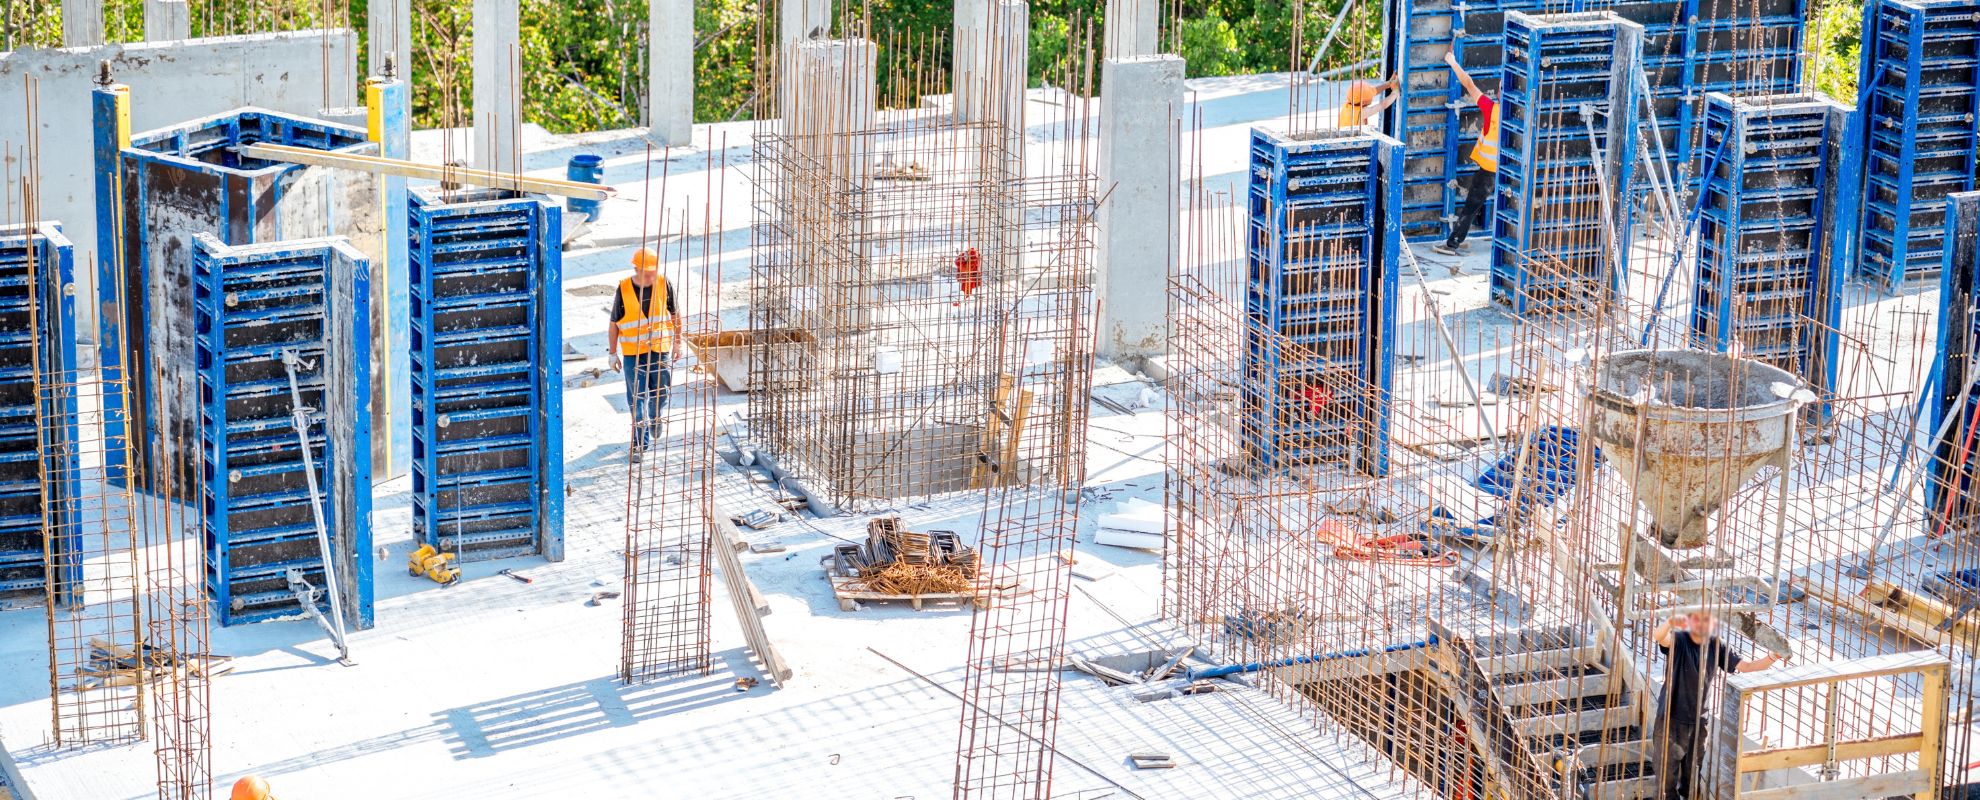
Typically 5 to 6 stages: slab/base, frame, lock-up, fit-out/fixing, and completion. Some contracts include a practical completion stage. Each stage must be inspected before the lender releases the next payment.
No. During construction you pay interest only on funds drawn to date. This significantly reduces your holding cost during the 8-to-14-month build period.
Yes. The lender values the finished dwelling and lends against that future value. You need council approval, a registered builder, a fixed-price contract and builder's insurance.
Typically 10% to 20% of the total project cost (land plus build). Some lenders accept 5% with LMI. The deposit is calculated on the as-if-complete value of the finished property.
Initial approval takes 2 to 4 weeks. Each progress payment claim takes 3 to 10 business days depending on the lender. Clarity Financial Solutions selects lenders with fast construction processing.
Yes. The $10,000 FHOG in Victoria applies to new builds under $750,000 and is paid at the first progress payment stage, reducing your borrowing amount.
This guide was prepared by Preeti Sidhu, Mortgage Broker at Clarity Financial Solutions (ACL 475676). Information is general in nature and does not constitute financial advice.
How do construction loans work in Melbourne is answered in this guide — from construction loan progress payments explained through to knock down rebuild finance process Melbourne. Clarity Financial Solutions manages the entire construction lending process across 40+ lenders at no cost. Book your free construction finance consultation today.
WhatsApp us